Hedge funds on the Chicago Mercantile Exchange flipped to a net long position in Bitcoin futures for the first time in years, a rare shift that breaks with the basis trade that has kept them structurally short. The move, flagged by data firm CryptoQuant, comes as the Coinbase Premium Index remains negative and open interest across exchanges sits near the lowest level of the past year.
The basis trade's usual posture
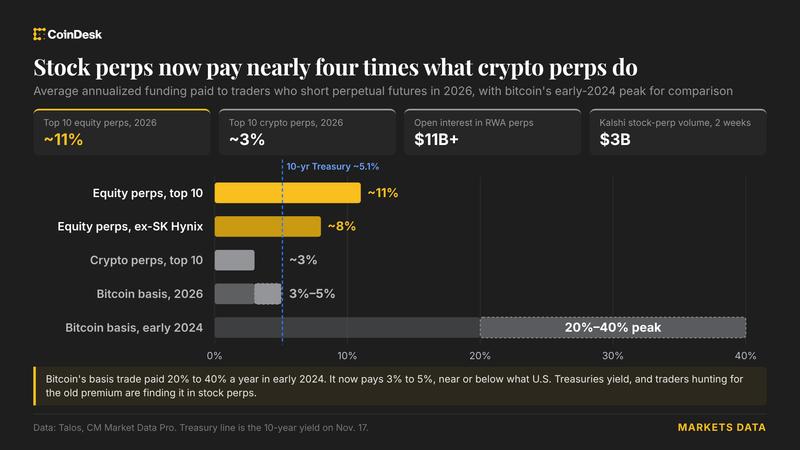
The basis trade is a market-neutral strategy where funds buy spot Bitcoin and sell CME futures, capturing the spread between the two. That positioning historically leaves hedge funds net short futures. The flip to net long suggests funds are either unwinding that trade or taking a directional bet. It's a notable change in posture, given how entrenched the basis trade has been.
Weak US demand
The Coinbase Premium Index, which tracks the price difference between Coinbase and other exchanges, has been negative since early May, near -0.08. It has made lower highs and lower lows since July 22, reinforcing soft US institutional demand. That's a headwind for any sustained rally. The index has been in negative territory for months, a sign that US buyers aren't stepping in with the same urgency as elsewhere.
Open interest near yearly lows
Open interest across all exchanges is near $23 billion, close to the lowest level of the past year, down from about $48 billion last October. It recovered slightly from a late-June low near $20.5 billion but remains weak. Thin open interest means less capital is committed to the market, and it can amplify price swings when positions are forced to close.
What the flip signals
The long positioning is notable, but it hasn't been confirmed by fresh capital. Bitcoin traded near $65,254 as the data circulated, little changed on the day. With US demand still soft and open interest thin, the market hasn't yet validated the shift. The question is whether the long flip is a leading indicator or a one-off repositioning.