Spark Finance grew its loan book 190% to $3 billion, the company said, making it the largest lender in decentralized finance even as the broader DeFi market contracted. The figures put Spark well ahead of rivals that have struggled to hold volume through the downturn.
The growth came from two places: stablecoin lending products and institutional clients. Both have proven stickier than the retail yield farming that drove earlier DeFi cycles.
Why Spark grew while the market shrank
Spark's numbers stand out because they run against the direction of the wider sector. Loan growth of 190% to $3 billion is not a small base effect. It's a lender pulling away from the pack.
The company's stablecoin offerings have been the main driver. Stablecoin lending doesn't carry the same directional price risk as volatile crypto collateral, which makes it easier to attract conservative borrowers and lenders who want yield without taking a view on token prices. That matters when the market is falling.
Institutional appeal is the other leg. Institutions need counterparties that can handle size and compliance requirements. Spark has positioned itself around those needs rather than chasing retail deposits with high-yield incentives.
Stablecoins as the quiet engine
The stablecoin market has held up better than the rest of DeFi through the contraction. That's given lenders like Spark a stable base of demand from borrowers who want dollar exposure without selling their crypto holdings.
Spark's $3 billion loan book is built on that demand. The company isn't relying on a single token or a single chain to get there. Diversification across stablecoin pairs and borrower types has kept utilization rates high enough to support the growth.
Competitors have tried the same approach. Few have matched Spark's scale. The difference appears to be execution on the institutional side, where relationships and operational reliability matter as much as rates.
What the shrinking DeFi market means for lenders
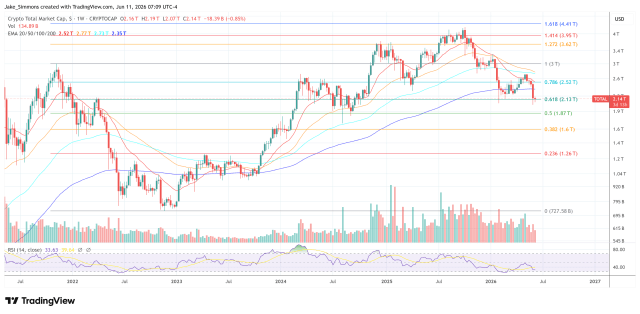
DeFi lending has always been cyclical. Total value locked rises and falls with token prices, and the past year has been mostly falling. Spark's growth during that period suggests the market is splitting: speculative lending is shrinking, while stablecoin-based credit is expanding.
That split has consequences. Lenders that built their books around volatile collateral have seen demand dry up. Lenders that built around stablecoins and institutional borrowers are capturing what's left of the growth.
Spark is now the clearest example of the second group. Its $3 billion loan book makes it the largest lender in the sector, a position that brings both visibility and scrutiny. Larger books mean larger risk management demands, especially if stablecoin flows reverse.
Spark hasn't said what it plans next. The company's lead is real, but it's built on a market segment that could attract more competition now that the model is working.
The next test is whether Spark can keep growing the book without loosening credit standards or relying on incentives that won't survive a change in rates. For now, the numbers speak for themselves: 190% growth to $3 billion while the rest of DeFi contracts.