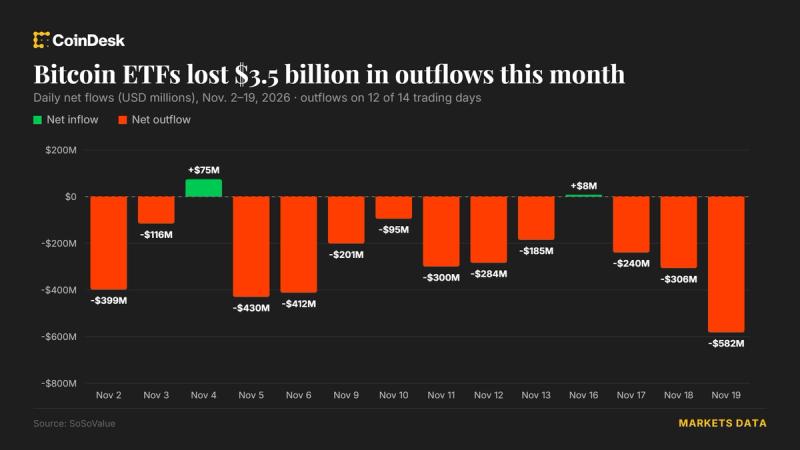
Roundhill has withdrawn its plans for two exchange-traded funds designed to generate income from Solana and XRP, according to the firm's latest filing. The move lands as spot crypto ETFs keep pulling in billions, yet demand for narrower, yield-focused crypto strategies is proving much harder to come by. The withdrawal leaves a visible gap between where the money is going and where product issuers had hoped to take it next.
What Roundhill was actually trying to sell
The two funds were structured around income generation, not plain-vanilla price exposure. That's a different pitch from the spot ETFs that have soaked up most of the capital in the space. Income products typically promise some sort of yield or premium-capture mechanism on top of the underlying asset. On paper, that should appeal to investors looking to squeeze more out of a crypto position. In practice, the audience for that kind of structure appears far smaller than the one for direct spot exposure.
Roundhill's decision to pull the plans rather than push ahead suggests the firm ran into the same wall its peers have hit: there just isn't much of a market for the more exotic end of the crypto ETF menu.
Rivals are seeing the same thing
Roundhill isn't alone in finding the door closed. Rival funds have flagged low demand for similar specialized crypto income ETF products, which makes the withdrawal look less like a one-off and more like a category problem. When several issuers independently report the same weak appetite, that's usually a signal rather than noise.
The contrast with the spot ETF complex is stark. Billions have flowed into plain spot crypto ETFs, and that money has to go somewhere. But the appetite doesn't automatically spill over into every new wrapper built on top of SOL or XRP. Income strategies add complexity, and complexity is a tougher sell when a simple spot product already does the job for most buyers.
The gap between spot flows and niche demand
That gap is the real story here. The spot crypto ETF market has become a large, liquid, well-understood destination for institutional and retail money alike. Income-generating products sit in a much thinner lane. They need investors who want yield, who understand the mechanics, and who are willing to take on the extra risk those mechanics usually carry. That's a narrower crowd than the one buying spot exposure.
For issuers, the math is unforgiving. Filing for an ETF is cheap relative to the cost of launching and marketing one that no one buys. Pulling the plug before that happens is the rational call, even if it stings.
What the withdrawal doesn't tell us
Roundhill didn't offer a detailed public explanation beyond the withdrawal itself, and the firm hasn't said whether it will refile with a different structure or refocus on other products. That leaves an open question: is this a temporary pause while the market matures, or a sign that specialized crypto income funds simply won't find a foothold in the current cycle?
The answer will probably come from the next batch of issuers testing the same idea. If more firms follow Roundhill out the door, the niche will look structurally weak. If others push ahead with tweaked designs, the category gets another shot. For now, the spot ETF machine keeps humming, and the income corner of the market is left waiting for a buyer base that hasn't shown up yet.